Depledge partners with Ansons Law and makes headline news
16 September 2026
Throughout the last few months, we’ve been advising clients about ways to prepare for the Inheritance Tax (IHT) and pension change that will be introduced in April 2027.
Because your pension could become part of your estate, the Inheritance Tax bill on your lifetime assets could be significantly higher than you’d accounted for, reducing the amount you leave to your loved ones.
Since the change directly relates to your pension savings, the new legislation might also impact your retirement plans.
As well as keeping families and individuals informed, we’ve also been working with law firms to help clients put the right legal structures and financial plans in place to protect their families’ wealth.
We’ve teamed up with Ansons Law to help clients put legal and financial plans in place
We’re delighted to have partnered with Ansons Law – a leading independent law firm trusted across Staffordshire and the West Midlands – to help more families prepare for a potential IHT bill and ensure more of their wealth reaches the next generation.
With frozen nil-rate bands already drawing more estates into the IHT net, both we and Ansons have seen a notable increase in clients seeking advice surrounding estate and succession planning.
While there are multiple strategies and planning options to help safeguard family wealth from HMRC, timely professional advice is often key.
Our partnership with Ansons means both firms are well-placed to ensure clients have the best possible financial and legal support.
Alongside our financial planning strategies – such as structured gifting, redirecting surplus funds into beneficiaries’ pension arrangements, or life cover – Ansons’ legal professionals are on hand to review wills and trusts, and advise clients on how their marital or civil partnership status could affect estate plans.
Andrew Day and Ansons Managing Director Martin De Ridder making headlines
As Andrew told FTAdviser, “By working with law firms like Ansons, we are helping our clients put the right legal structures and financial plans in place to protect their families’ wealth.”
Speaking to FTAdviser about the partnership with Depledge, Martin De Ridder, Managing Director of Ansons, said: “As well as wills, trusts, and probate services, we are increasingly helping clients with estate planning, asset protection, and long-term succession planning to safeguard their family’s financial future […] For some people, the changes in April 2027 will be potentially disastrous if they do not seek expert financial planning advice alongside sound legal counsel.”
De Ridder also reiterated the possible “double whammy” tax bill – where both IHT and Income Tax could be payable on inherited pensions, saying: “Additional-rate taxpayers could face an effective tax rate of 67% […] That’s a brutal shock if you’re not prepared, which is why we’re working with expert financial planners like Depledge to ensure our clients have a plan in place for when this IHT storm hits.”
Bear in mind that tax treatment will depend on individual circumstances and may change in the future. Plus, as a long-term investment, pension savings may fluctuate and can go down. This may affect the level of pension benefits available.
Here are just a few of the headlines and article links to publications that shared news of our partnership with Ansons Law:
- FTAdviser: Law and advice firms team up on ‘potentially disastrous’ pension IHT changes
- IFA Magazine: Law firm teams up with wealth manager as “potentially disastrous” inheritance tax hike looms
- Solicitors Journal: Law firm partners with wealth manager to tackle inheritance tax challenges
The potential tax cost when pensions are included in Inheritance Tax calculations
FTAdviser shared a succinct example of the potentially costly tax charges that clients and their families could face.
A £1 million unspent pension could be taxed from April 2027 as follows:
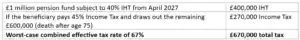
IFA Magazine followed a similar eye-watering example with an encouraging anecdote from Andrew about one Depledge client who had “managed to reduce his immediate tax exposure ahead of next April’s law change by entering into a civil partnership with his long-term partner.”
The story exemplifies that “effective planning options do exist, but they require timely professional advice.”
Here to help you prepare for the upcoming rule change
Since pensions have not previously been subject to IHT, they have often been used as a helpful, tax-efficient way for affluent families and individuals to transfer wealth to the next generation.
From April 2027, your pension savings could become subject to IHT at a rate of 40%. The charge will apply to sums that exceed the nil-rate band – £325,000 in 2026/27.
If your pension forms an integral part of your estate plan, please get in touch. We’ll work with you to review your plan and explain strategies that could help to reduce the value of your estate before your death.
Get in touch
To speak to an independent financial planner about IHT, or any other financial matter, email [email protected] or call 0161 8080200.
Please note
This article is for general information only and does not constitute advice. The information is aimed at individuals only.
All information is correct at the time of writing and is subject to change in the future.
Levels, bases of and reliefs from taxation may be subject to change and their value depends on the individual circumstances of the investor.
The Financial Conduct Authority does not regulate estate planning or tax advice.